📊 Full opportunity report: AI Adoption: A Slow Start With Long-lasting Impact on ThorstenMeyerAI.com — validation score, market gap, and execution plan.
TL;DR
Enterprise AI adoption remains sluggish, with most pilots failing and internal resistance high. Yet, established vendors like Microsoft and SAP dominate, leveraging their entrenched data and systems to maintain control. This slow pace creates durable moats that make disruption difficult, even as AI’s influence grows.
Despite widespread predictions of rapid AI-driven disruption, enterprise AI adoption remains slow, with 95% of pilots delivering no substantial results, according to industry analysis. Meanwhile, incumbent vendors like Microsoft and SAP continue to dominate the market, embedding AI deeply into their existing platforms, which reinforces their market control and resilience.
Research indicates that most enterprises struggle to move beyond initial AI pilots due to organizational inertia, internal resistance, and high switching costs. Notably, the platforms that attract the most AI investment are not disruptors but established players such as Microsoft with its Copilot integration in Microsoft 365, Salesforce’s Agentforce, and SAP’s Joule. These incumbents have effectively become the ‘operational control planes’ for enterprise AI, embedding trusted data and governance into core workflows.
According to industry analysts, the structural advantages of incumbents—such as data gravity, regulatory compliance, and deep integration—make them difficult to displace. Despite the slow pace of adoption, these firms are capturing most of the value, as their existing relationships and data assets create high switching costs, effectively turning their conservatism into a competitive moat. This dynamic has led to a convergence in architecture across vendors, with most shipping similar AI-enabled agent systems built on trusted enterprise data.
Incumbents are painfully slow to adopt AI — and remarkably hard to displace. How can both be true? They’re the same fact wearing two faces.
- 95% of pilots deliver nothing
- The internal customer resists
- Two-year timelines to change
- Built to resist transformation
- Absorb most enterprise AI spend
- Became the “control planes”
- Two years no rival can rip it away
- BCG: “a clear right to win”
Implications of Incumbent Dominance in Enterprise AI
This situation underscores that the slow adoption of AI is not a weakness but a strategic advantage for established vendors. Their entrenched systems and data assets create high barriers to exit, making them resilient against disruption despite their sluggish pace. For enterprises, this means that AI-driven change will likely reinforce existing market structures rather than dismantle them quickly, influencing how businesses plan their digital transformation and vendor relationships.
As an affiliate, we earn on qualifying purchases.
Enterprise AI Adoption Trends and Market Dynamics
Since 2024, industry reports have documented a pattern of slow, pilot-heavy AI initiatives that rarely scale. While early predictions suggested rapid disruption, the reality has been a cautious, incremental integration by incumbents. Major vendors like Microsoft, SAP, and Salesforce have shifted from competing on differentiation to converging on similar AI architectures, prioritizing governance and trusted data integration. This reflects a broader trend of AI becoming embedded into core enterprise systems, rather than replacing them outright.
"The slowness of enterprise AI adoption is both a sign of organizational inertia and a source of enduring market power for incumbents."
— Thorsten Meyer
AI integration platforms for businesses
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Unclear Impact of Future AI Innovation on Market Power
It remains uncertain how future breakthroughs in AI technology or shifts in enterprise priorities might alter the current landscape. While incumbents are currently benefiting from their entrenched positions, it is not yet clear whether they will sustain this dominance if new, more disruptive AI models or architectures emerge that can bypass existing data and governance barriers.
AI governance and data management solutions
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Next Steps in Enterprise AI Development and Market Shifts
Industry observers anticipate ongoing consolidation around existing platforms, with incumbents continuing to embed AI into their core offerings. Future developments may include more unified AI architectures and enhanced governance features. Monitoring how enterprises adapt their strategies and whether new entrants can overcome the high switching costs will be key to understanding the evolving competitive landscape.
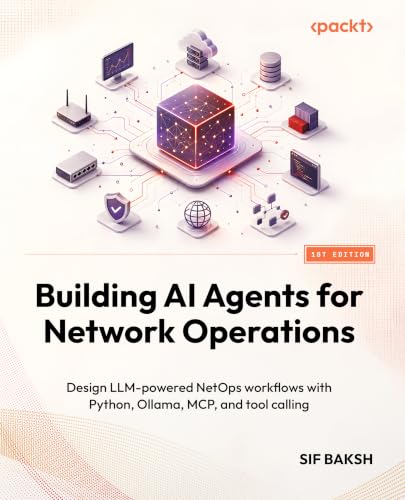
Building AI Agents for Network Operations: Design LLM-powered NetOps workflows with Python, Ollama, MCP, and tool calling
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Key Questions
Why is enterprise AI adoption so slow?
Most enterprises face organizational inertia, internal resistance, and high switching costs, which hinder rapid adoption beyond initial pilots.
Do incumbents have an advantage over AI-native disruptors?
Yes, incumbents benefit from entrenched data, governance, and integration, creating high barriers for disruptors to displace them quickly.
Will slow adoption eventually lead to disruption?
It is uncertain; while slow adoption reinforces incumbents' market power now, future technological breakthroughs could challenge this dynamic.
What does this mean for enterprise digital transformation?
Enterprises are likely to see incremental AI integration within existing systems, with major vendors consolidating their control rather than enabling rapid market upheaval.
Source: ThorstenMeyerAI.com